

Key Takeaways
- Net worth equals total assets minus total liabilities.
- A negative net worth is common, especially early in adult life, and is not a permanent condition.
- Tracking net worth over time shows whether your overall financial position is improving.
- Net worth does not capture income or cash flow, so it works best alongside a budget or spending tracker.
- You do not need special software to calculate net worth; a spreadsheet or pen and paper works fine.
Net worth
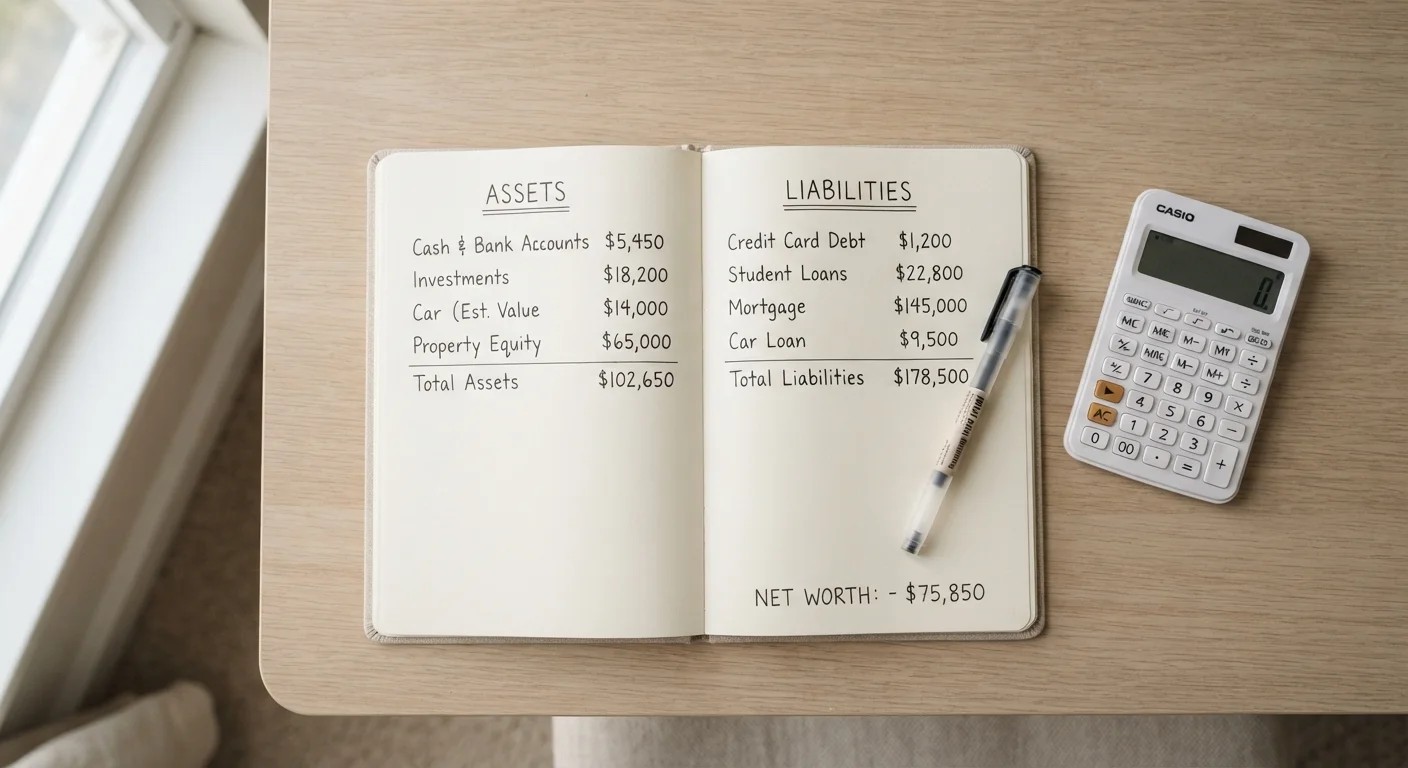
Net worth is the dollar amount left when you subtract everything you owe (your liabilities) from everything you own (your assets). If your assets total $150,000 and your debts total $90,000, your net worth is $60,000. The number can be positive or negative, and it changes over time as you save, invest, or pay down debt.
Net worth is a point-in-time snapshot, not a cash-flow measure. It does not reflect income, monthly spending, or liquidity.
The basic formula
Net worth has one equation: assets minus liabilities. Assets are things you own that have monetary value. Liabilities are amounts you owe to others. Subtract the second from the first and you have your net worth.
Assets to count include bank account balances, retirement and brokerage account balances, the current market value of real estate, vehicle values, and any other property you could convert to cash. Liabilities include mortgage balances, auto loans, student loans, credit card balances, and any other debt you carry.
The result can be positive or negative. A positive net worth means your assets outweigh your debts. A negative number means the reverse. Neither outcome is permanent; both change as your financial situation evolves.
For a broader introduction to personal finance vocabulary, see common financial terms explained.
Why the number is worth tracking
A single net worth calculation tells you where you stand today. A series of calculations tells you whether your position is getting stronger or weaker over time. That trend is what makes the metric useful.
Monthly income and spending figures show short-term cash flow. Net worth shows the cumulative effect of all your financial decisions: how much debt you have paid down, how much you have saved, and how your assets have changed in value. A person can have a good income and still see net worth stagnate if spending keeps pace with earnings and savings do not grow.
Tracking the number creates a feedback loop. If net worth is rising consistently, that confirms the current approach is working. If it is flat or falling despite a stable income, that signals something in the financial picture, debt growth, poor savings rate, or asset losses, warrants attention.
$192,700
Median US household net worth (ages 35-44)
According to the Federal Reserve's Survey of Consumer Finances, published in 2023 using 2022 data.
$39,040
Median US household net worth (under age 35)
Federal Reserve Survey of Consumer Finances, 2023, reflecting the lower asset accumulation typical early in adult financial life.
1 in 5
US families with zero or negative net worth
Federal Reserve Survey of Consumer Finances, 2023, illustrating how common a negative or zero net worth position is across American households.
Net worth works best alongside other tools. A budget sets spending intentions; a spending tracker records what actually happened. For more on how those two tools differ, see the difference between a budget and a spending tracker.
Common mistakes in the calculation
Using purchase price instead of current market value overstates assets. A car bought for $30,000 three years ago may now be worth $18,000. Use the value it would fetch today, not what you paid.
Forgetting small debts understates liabilities. Medical bills, a family loan, or a store credit card with a small balance all count. Omitting them produces a net worth figure that looks better than it is.
Counting illiquid assets at full face value without noting their liquidity can be misleading. A retirement account balance is real, but early withdrawal penalties and taxes mean the spendable amount is lower. That does not mean you should exclude it; just keep the distinction in mind when interpreting the total.
A practical system for tracking daily spending can help you stay on top of the liability side by making it easier to see where balances are growing.
How to do the calculation without special tools
A spreadsheet with two columns, one for assets and one for liabilities, is sufficient. List each item with its current value, total each column, and subtract. The whole process takes under 30 minutes the first time and much less once the list is set up.
After the first calculation, the main task is updating balances. Account balances change monthly; asset values such as home or vehicle worth change more slowly and can be updated quarterly. Most people find that a monthly update covering financial accounts and a quarterly refresh of property values gives a clear enough picture without becoming a chore.
For a related exercise in reading your financial accounts clearly, the walkthrough of your bank statement covers what each line actually means.
This article is for general informational purposes only and does not constitute personalised financial advice. Consult a licensed financial adviser for guidance specific to your situation.