

Key Takeaways
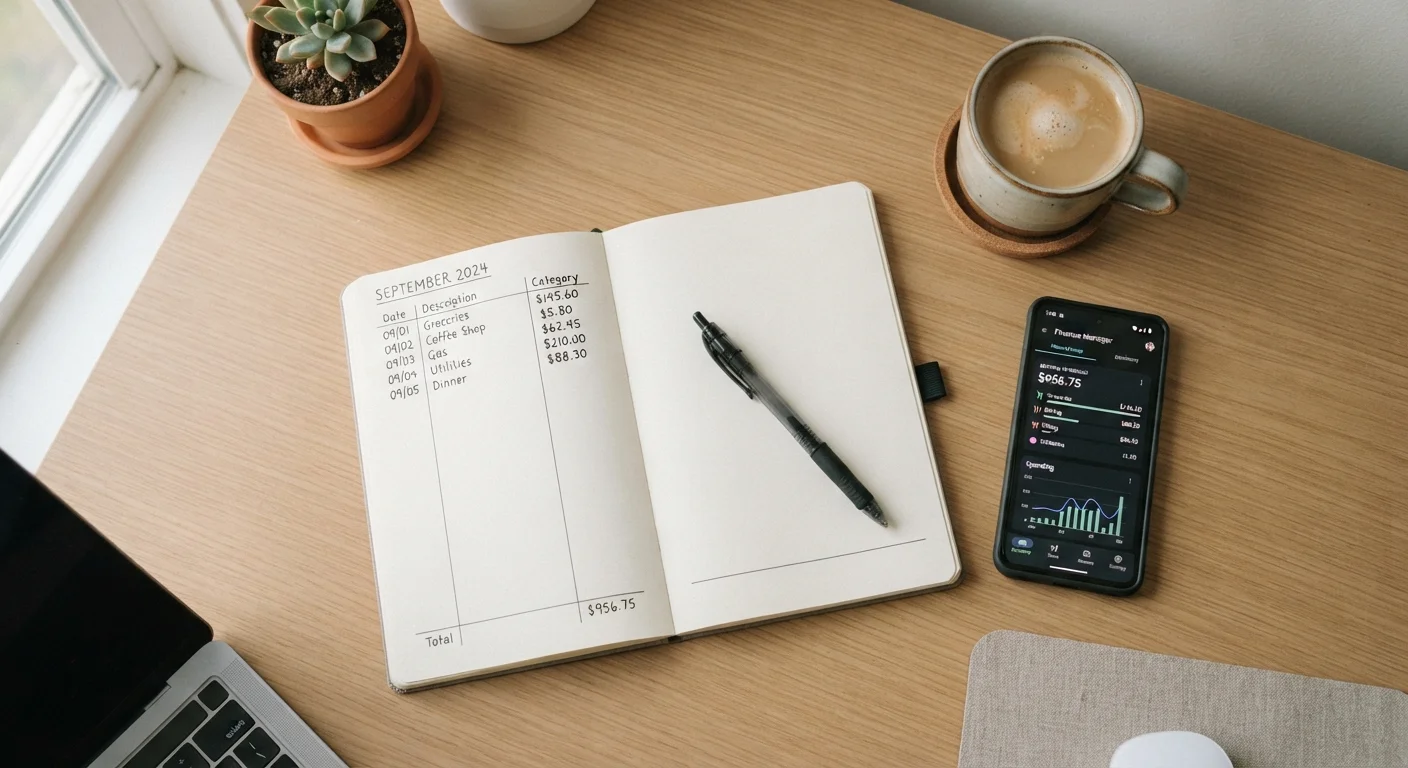
- Recording every expense daily, rather than weekly, catches small purchases before they disappear from memory.
- Grouping expenses into a consistent set of categories is what makes patterns visible over time.
- A weekly five-minute review turns raw data into decisions you can actually act on.
- You do not need a paid app to track spending; a notebook or a free spreadsheet works just as well.
- Consistency matters more than the tool you choose.
What you will need
Why daily tracking beats monthly reviews
Most people review their spending once a month, usually when a bank statement arrives or a budget feels tight. By that point, dozens of small transactions have lost all context. You can see that $47 left your account at a coffee shop over four weeks, but you cannot recall which visits were work meetings and which were impulse stops. The money is gone either way, but the pattern that drove it is invisible.
Daily tracking closes that gap. When you record a purchase within hours, you still remember why you made it. That context is what turns a list of numbers into something you can interpret. It is also what separates a spending tracker from a bank statement. A budget plans ahead; a tracker records what actually happened, and the tracker's value depends entirely on the accuracy of its entries.
Small daily purchases add up faster than most people expect. A $4 purchase repeated five days a week becomes over $1,000 a year. Daily tracking makes that math visible before it becomes a surprise.
What you need before you start
The right setup is the one you will actually use. Choose a format that fits your routine, not one that looks good in theory.
What you will need
Notebook or pocket journal
Records expenses by hand immediately after a purchase, no battery or connectivity required.
Spreadsheet (free, browser-based)
Lets you total and sort entries by category without any subscription cost.
Budgeting or expense-tracking app
Automates entry for card transactions and generates category summaries automatically.
Bank or credit card statements
Serves as a cross-check to catch any purchases you forgot to record manually.
How to build your daily tracking system
Follow these steps to establish a reliable habit. The first week will feel effortful; the second week will feel routine.
Choose one recording method and commit to it
Pick either a physical notebook, a spreadsheet, or an app. The method matters less than the consistency. If you switch formats mid-month, you will have incomplete records and the pattern data becomes unreliable. Decide before Day 1 and stay with it for at least 30 days.
Define your spending categories
Write down six to eight categories that reflect your real spending life. Common ones include: housing, groceries, transportation, dining out, subscriptions, personal care, health, and miscellaneous. Every future entry will fall into one of these buckets, so make them broad enough that you are not creating new categories every week.
Record each purchase within the same day
Log the amount, the category, and a one-word note about what it was. Example: $6.50, Dining Out, coffee. That is all the detail you need. Do not wait until the weekend to batch-enter a week's worth of receipts. Memory fades fast, and a batch entry turns the tracker into guesswork rather than a record.
Set a fixed daily logging time
Choose a specific time each day to review and complete your entries: after dinner, before bed, or during a commute home. A fixed trigger removes the decision about when to do it, which is what makes the habit stick. Even on a day where you spend nothing, open your tracker and confirm that the entry is zero. That confirmation builds the reflex.
Run a weekly five-minute category review
At the same time each week, total your entries by category and compare them to the previous week. You are looking for any category that jumped noticeably. Do not judge the number; identify whether the jump was expected (a car repair, a birthday gift) or unplanned. Unplanned spikes are the information you are tracking toward.
Cross-check against your bank statement at month-end
Download your bank and credit card statements and compare the totals to your tracker. Any gap between what the statement shows and what your tracker recorded is either a missed entry or a transaction you did not recognize. Investigate both. This step confirms that your tracker is complete, not just consistent.
Turning records into useful information
Raw expense data is just a list until you organize it into categories. Good categories match your actual life: rent, groceries, transportation, dining out, subscriptions, personal care, and a catch-all for everything else. Keep the list short. Too many categories create friction; too few hide the patterns you are trying to see.
Once a week, spend five minutes scanning your entries. Look for categories that ran higher than you expected, one-off expenses that will not repeat, and recurring charges you had forgotten about. This is the review step that converts tracking into awareness. For a structured approach to that review, the weekly money check-in habit guide walks through a short, repeatable process.
At month-end, the full picture becomes clear. Before closing the books on any month, a monthly spending audit helps confirm that subscriptions, recurring bills, and discretionary spending all landed where you expected. If you use digital tools to support this process, digital tools for everyday finance tasks covers the main categories without steering you toward any specific product.
Tracking daily spending also pairs well with other budgeting methods. The envelope method uses fixed category limits that become much easier to manage when your tracker tells you exactly where you stand each day. And if you want to use your bank statement as a cross-check, reading a bank statement as a budgeting tool explains how to compare it against your own records strategically.
This article provides general financial information for educational purposes and does not constitute personalised financial advice. Consult a qualified financial adviser for guidance tailored to your individual circumstances.