

Key Takeaways
- A weekly check-in works best when it is short, consistent, and tied to a specific day and time.
- You only need to review four things: account balances, recent spending, upcoming bills, and one short-term goal.
- Habit stacking, pairing the check-in with an existing routine, is the most reliable way to make it stick.
- Automation handles repetitive tasks, but it does not replace the awareness a weekly review provides.
- Missing one session does not break the habit; resuming promptly is what matters.
What you will need
Why a weekly check-in works when monthly reviews do not
Monthly budget reviews are common advice, but a month is long enough for a small spending drift to compound into a real shortfall before you catch it. A weekly session, kept under 20 minutes, surfaces problems while they are still small and correctable.
The other advantage is frequency. A habit that runs once a month has fewer opportunities to become automatic. Weekly repetition builds the neural associations that make a behavior feel routine rather than effortful. The same principle applies across habit types, as explored in why small, consistent habits outperform dramatic lifestyle overhauls.
This article is general financial information and education, not personalized financial advice. For decisions specific to your situation, consult a qualified financial professional.
What you will need
How to run your weekly check-in
Bank or credit union online portal
View recent transactions and current balances during the check-in.
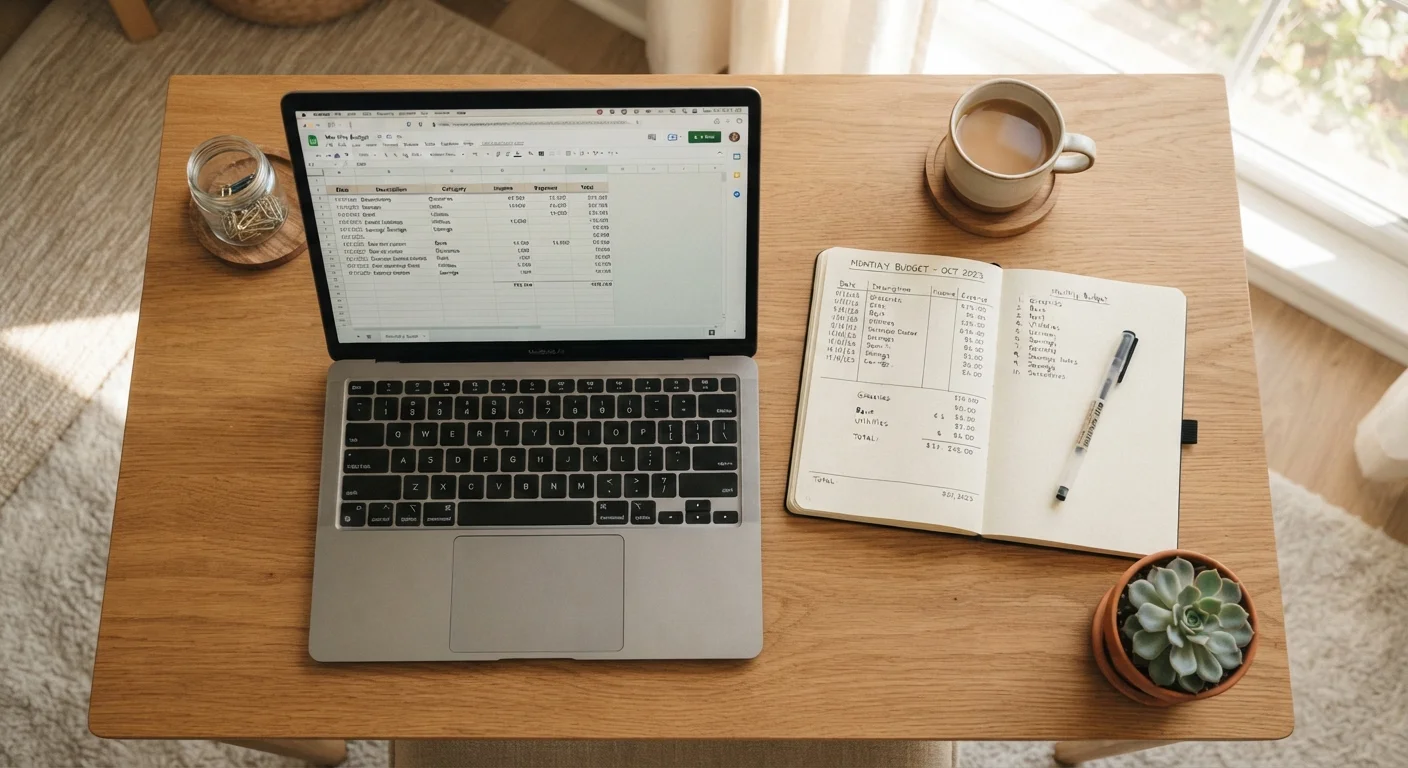
Spreadsheet or budgeting notebook
Record weekly totals and flag any spending that exceeded your plan.
Phone calendar or reminder app
Schedule a recurring weekly alert so the check-in does not get skipped.
Personal finance app
Aggregates transactions from multiple accounts in one place, reducing manual data entry.
Pick a fixed day, time, and location
Choose a specific slot you can protect every week. Sunday evenings and Monday mornings work for many people because they sit naturally at a week boundary. The location matters too: a quiet spot with no distractions shortens the session and reduces the chance you abandon it mid-way.
Set a recurring calendar reminder the moment you decide on the slot. Treating it like a standing appointment makes it harder to skip.
Pull up your accounts and note your balances
Log in to each bank, credit union, and credit card account. Write down the current balance for each. You are not analyzing anything yet; you are simply taking a snapshot. This step takes two to three minutes and gives you an accurate baseline before you look at spending patterns.
Review the past seven days of spending
Scan every transaction from the past week and group them loosely into categories: groceries, dining, transport, subscriptions, and discretionary purchases. You do not need precise accounting. The goal is to spot anything that surprised you or exceeded your informal budget for that category.
For a deeper look at subscriptions and recurring charges that can silently drain accounts, see the monthly spending audit checklist.
Check what bills are due in the next seven days
Look at your calendar or bill-pay portal and confirm every payment scheduled for the coming week. Cross-reference the amount against your current balances to confirm you have enough to cover each one without overdrafting.
If you have not yet automated routine bill payments, automating your finances can remove this as a weekly worry while you focus the check-in on awareness, not logistics.
Note progress on one short-term financial goal
Identify one goal you are actively working toward, whether that is building an emergency fund, paying down a credit card balance, or saving for a specific purchase. Record how much you have set aside this week and whether you are on track relative to your target. Keeping this to one goal prevents the check-in from expanding into an overwhelming planning session.
If you are still deciding what to prioritize, the budgeting basics hub covers common frameworks for setting spending and saving targets.
Write down one adjustment for the coming week
Close each session with a single concrete change. This could be as small as cooking dinner at home twice instead of once, or delaying a non-essential purchase until the following week. One adjustment is enough. Multiple resolutions rarely survive contact with a normal week.
Keeping the habit alive after the first few weeks
Most financial routines collapse between weeks three and six, when the novelty fades and competing demands fill the calendar. A few structural choices reduce that risk.
First, keep the session short on purpose. Letting it run past 25 minutes turns it into a chore. If you find yourself deep in analysis, stop and schedule a separate longer session. The weekly check-in is for awareness, not overhaul.
Second, log your streak somewhere visible. A simple tally in your notebook of consecutive weeks completed gives you a concrete reason to resume after a missed session rather than abandoning the habit entirely. Missing one week is not failure; skipping the following week because you already broke the streak is where habits die.
Third, connect the check-in to your broader money picture over time. After four to six weeks you will have enough data to recognize your real spending patterns, which makes the end-of-month spending audit faster and more accurate. The two routines complement each other: weekly awareness feeds monthly precision.
For readers also working on building an emergency fund inside a budget, the weekly check-in is the mechanism that keeps those small, consistent contributions on track without requiring daily attention.
If motivation drops, shrink the task
On weeks when time is short or energy is low, do only step two and step three: check your balances and scan your transactions. Two minutes of awareness is more useful than skipping the session entirely. A reduced check-in still keeps the habit alive.
This article is for general informational purposes only and does not constitute personalized financial, tax, or legal advice. Consult a licensed financial professional for guidance specific to your circumstances.